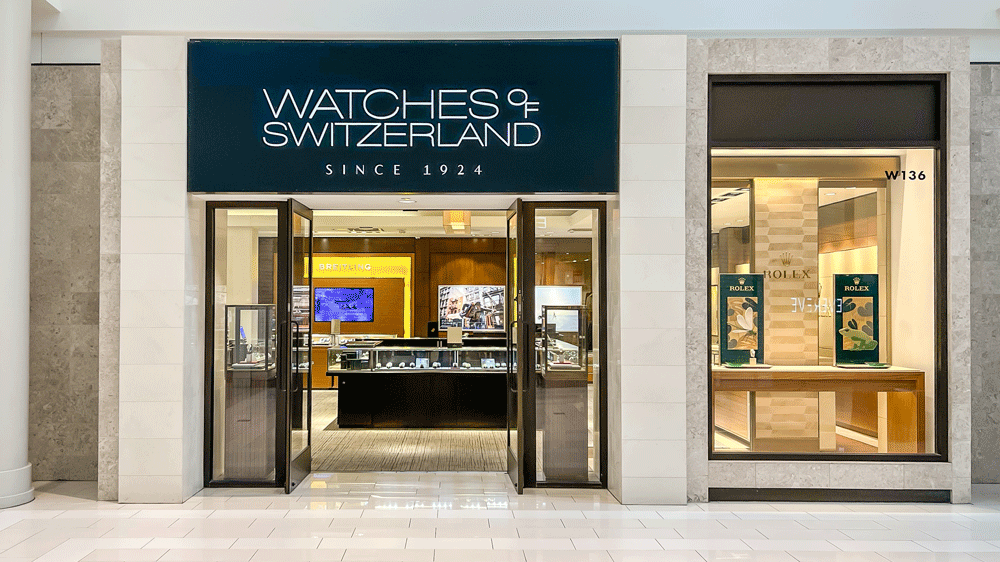
A profitability shift buried inside Watches of Switzerland Group’s H2 2026 results may be the single most important fact behind one of the luxury sector’s sharpest share price runs.
The company posted £982.8m in revenue for the period, but the more striking figure was net margin climbing to 5.5%, nearly double the 2.9% recorded in the same period a year earlier.
That margin expansion translated into £54.4m in net income and gave concrete weight to what had been, twelve months ago, merely an optimistic assumption among analysts tracking the business.
Shareholders who held through the uncertainty collected an 86.1% total return including dividends, measured from a starting price of £4.03 per share to the current level of £7.47.
The climb was not obvious at the outset, because investors weighing the stock in late 2025 were confronted with two sharply opposing views built on the same underlying facts.
Optimists pointed to a fair value of £4.54, anchored in expectations for measured US showroom growth, luxury jewelry expansion, and margin improvement supported by acquisitions including Hodinkee and Roberto Coin.
Skeptics countered with a fair value of £3.60, arguing that tariff exposure, dependence on a small group of Swiss watch brands, and luxury houses accelerating direct-to-consumer strategies posed genuine structural risks.
The H2 2026 results did not eliminate the cautious argument entirely, since premium valuation concerns from brokers kept the debate over further upside very much alive.
What the results did do was validate the core bull thesis: that Watches of Switzerland was capable of extracting meaningfully higher margins as its distribution model matured and its jewelry segment grew.
The question investors now face is whether £7.47 already reflects that story in full, or whether the underlying business can continue expanding at the pace the current price implies.
Proponents of the stock frame it in terms that go well beyond conventional retail, with one assessment stating: “Watches of Switzerland Group (LSE: WOSG) is not a retailer. It is the dominant distributor of scarce luxury goods in the world’s largest and fastest-growing luxury watch market, with a nascent high-margin jewellery distribution business that the market has not yet begun to price correctly.”
That framing positions US luxury watch market dominance and the jewellery distribution segment as two distinct growth levers, each with room to compound before the market fully prices them in.
Whether those levers can sustain the operational scale the narrative demands is the central analytical question for anyone considering the stock at current levels.
The broader lesson from this run is straightforward: when a thesis depends on margin expansion, the net margin line in each results cycle deserves more attention than the share price movement alone.
WOSG.L slipped 1.58% in the most recent session, a modest pullback that does little to alter the scale of gains accumulated over the preceding twelve months.