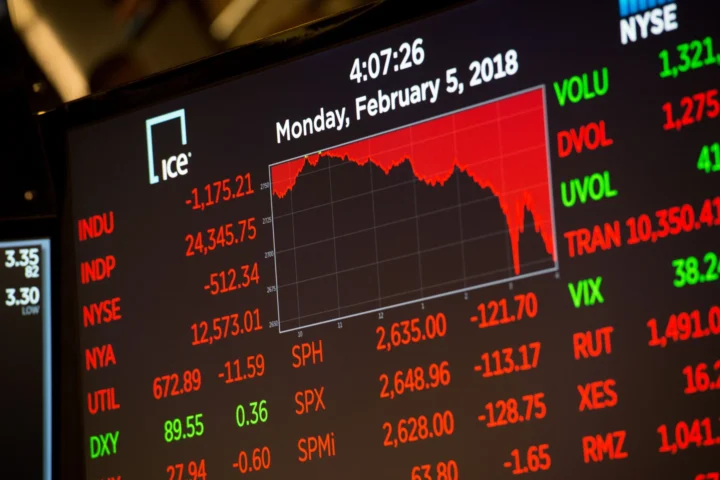
Last week ranked as the worst stretch for chip stocks in more than a year, hammering the sector with a brutal and widespread sell-off.
The Philadelphia Semiconductor Index dropped more than 11%, driven by a hot inflation print that raised the cost of funding data center projects across the industry.
Fears surrounding CoreWeave’s debt load spread quickly, casting a shadow over every company with exposure to AI infrastructure spending.
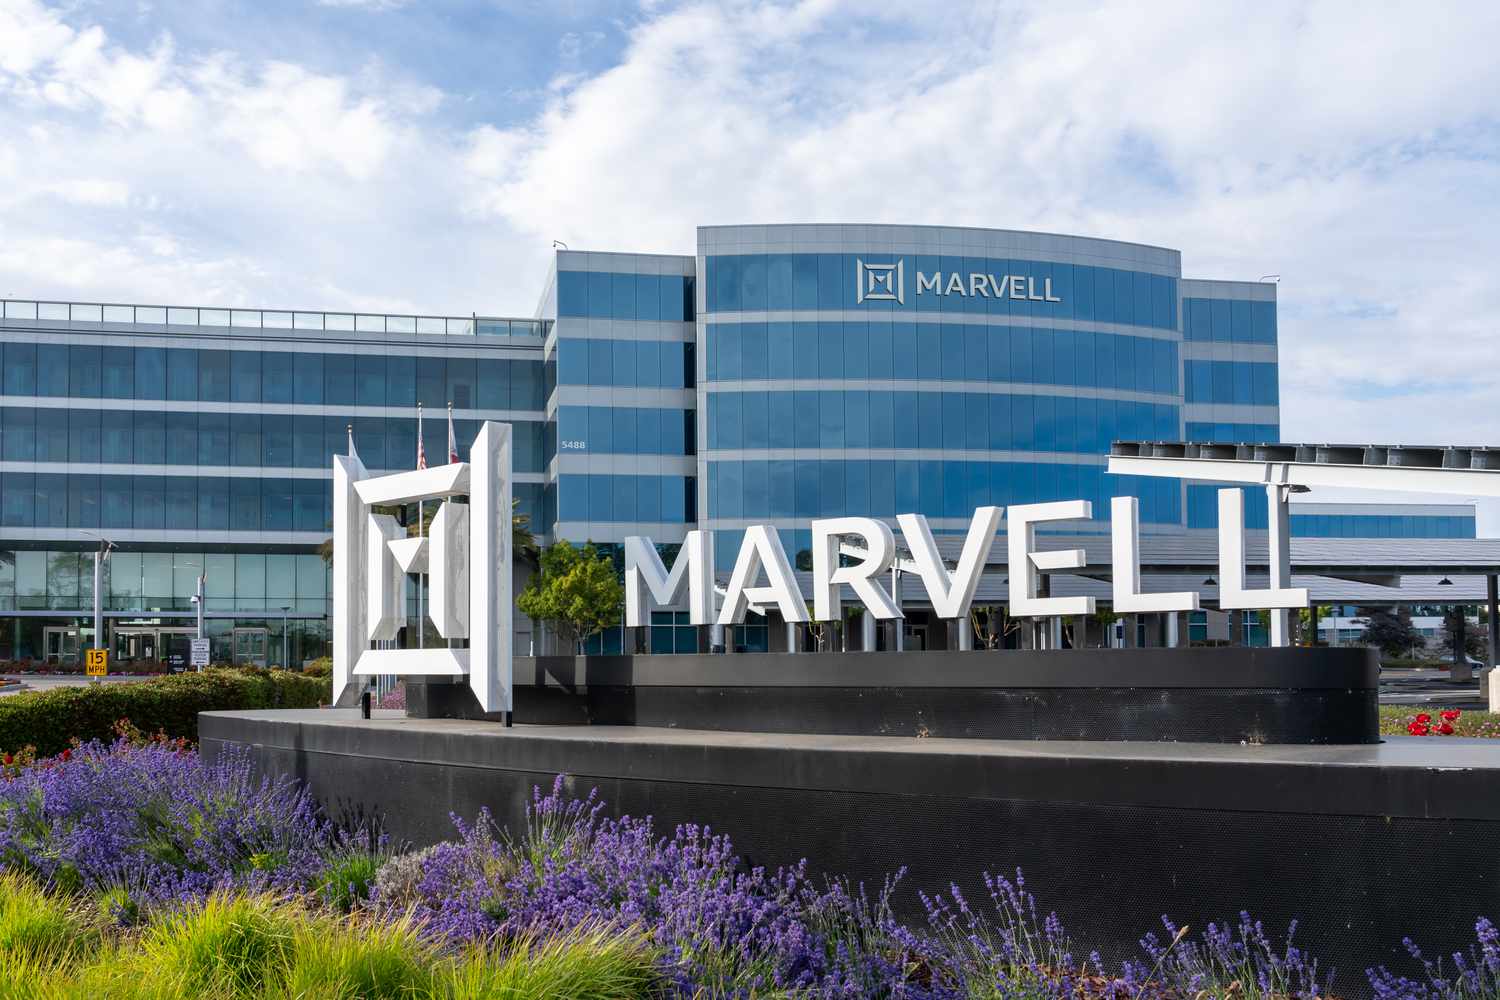
Marvell Technology (NASDAQ: MRVL) was caught squarely in the downdraft, sinking nearly 17% over just five trading days.
Yet while investors were rushing for the exits, Marvell was quietly unveiling some of its most significant product-level work of the year at the OCP Summit.
The company introduced its second generation of Structera X memory expanders, designed to tackle what Marvell calls the “memory wall” in AI inference workloads.
As AI models grow larger and context windows extend further, GPUs frequently exhaust available memory before they exhaust their computational capacity, creating a critical performance bottleneck.
Structera X addresses that problem directly, allowing a server to attach up to 6 terabytes of standard DDR5 memory, share it across four hosts, and compress data on the fly.
Marvell says this configuration cuts time to first token by 40% to 50%, a meaningful performance improvement for large-scale AI inference deployments.
The first generation of Structera X is already shipping to hyperscalers, with a Meta Platforms hardware engineering director quoted in the company’s official release.
Test models of the second-generation chip are expected to be available in the first quarter of 2027, keeping Marvell on a steady product cadence.
Marvell also introduced new 3-nanometer connectivity chips designed to help racks of accelerators communicate over longer copper cables without signal degradation.
These two product categories together target the two most persistent hardware constraints limiting AI processor performance: memory access and inter-chip communication speed.
On October 6, Marvell held its first investor day in years, where management outlined a revenue target in the range of $70 billion to $90 billion by fiscal 2031.
That figure represents a dramatic expansion from the $8.2 billion Marvell posted in fiscal 2026, with implied non-GAAP earnings above $30 per share embedded in the forecast.
Reaching that target requires roughly 55% to 60% annualized growth sustained over five years, which warrants healthy skepticism from any serious investor.
Even at half that growth rate, however, the stock near $228 looks compelling against the company’s own long-term earnings projections.
Nvidia reinforced confidence in Marvell’s trajectory by purchasing $2 billion of Marvell preferred stock in March, a move Nvidia does not make lightly or casually.
Risks remain real: Marvell trades at a high trailing earnings multiple, custom chip revenue is lumpy, and the company is tied closely to a small number of hyperscaler customers.
If those customers pull back due to rising borrowing costs, Marvell would likely feel the pressure before Nvidia does, given its concentrated revenue exposure.
Last week’s sell-off, however, was rooted in financing fears rather than any sign of customers actually reducing orders or walking away from commitments.
For investors with the conviction to hold through 2027 and beyond, the 17% discount the market handed them last week looks like a significant opportunity.