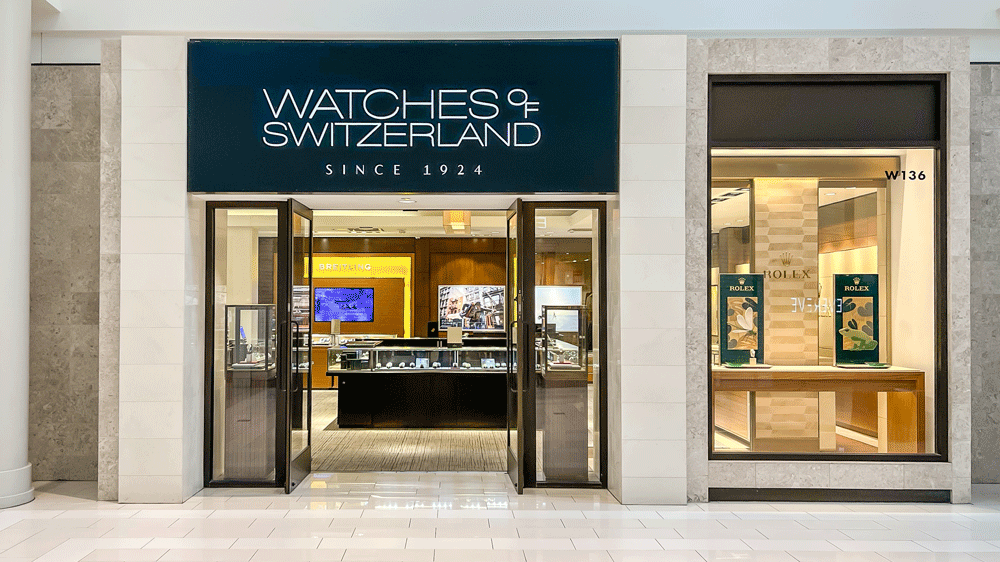
Watches of Switzerland Group PLC (LSE:WOSG) has retained a “sector perform” rating from RBC Capital Markets, which also maintained its 800p price target on the luxury watch retailer.
RBC expects the company to deliver first-half 2026/27 revenue of £943 million, representing growth of 12% on a reported basis and 8% at constant currencies.
The broker’s forecast comes ahead of the company’s trading update scheduled for 10 November, which investors will be watching closely for signs of continued momentum.
US revenue is forecast to climb 23% to £502 million, including like-for-like growth of 8%, reflecting strong American appetite for luxury timepieces.
UK and European revenue is expected to edge 1% higher to £441 million, with like-for-like growth of 5%, a more modest but still positive trajectory for the domestic market.
RBC forecasts adjusted operating profit of £81 million for the first half, representing a margin of approximately 9%, alongside diluted earnings per share of around 24p.
Recent Swiss watch export data has remained supportive of the broader sector, with three-month growth reaching 24% in the US and 13% in the UK, according to RBC.
Demand for watches priced above CHF3,000 has also improved, which is particularly significant for Watches of Switzerland given that roughly half of group revenue is tied to Rolex.
Despite the encouraging market backdrop, RBC cautioned that the retailer’s shares now trade at around 13 times forward earnings, above the longer-term historical average of approximately 11 times.
The shares have gained 36% over the past six months, a rally that the broker believes has already absorbed much of the positive news surrounding the business.
RBC noted that this elevated valuation leaves limited room for further re-rating unless the company delivers meaningful earnings upgrades beyond current expectations.
For the full 2026/27 financial year, RBC projects revenue of around £2 billion and adjusted operating profit of £179 million, reflecting confidence in the group’s underlying growth trajectory.
The broker’s 800p price target implies approximately 13% upside from the share price used in its report, offering a balanced but not compelling risk-reward profile at current levels.