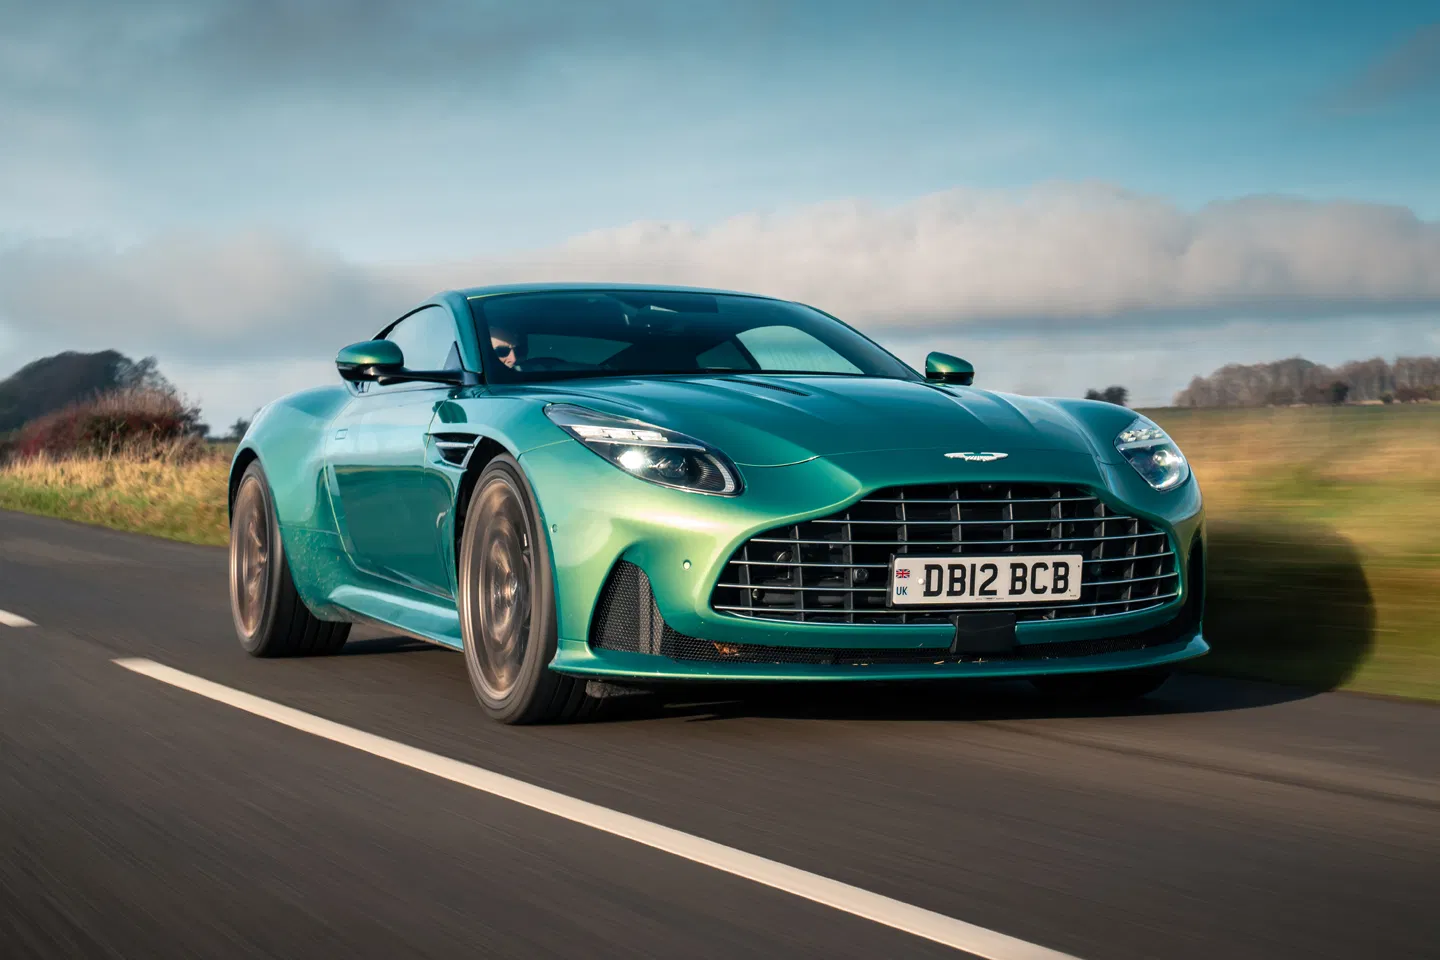
Aston Martin’s third-quarter adjusted pre-tax loss came in at £75.6 million, overshooting the average analyst estimate of £60 million and raising questions about rising debt costs.
Financing expenses have become a growing burden, with the luxury carmaker’s adjusted net financing costs for the first nine months climbing to £149 million, compared with just £65 million in the same period a year earlier.
A significant portion of that increase stemmed from an £11 million non-cash charge related to the revaluation of U.S. dollar-denominated debt, reversing a £58 million gain recorded in the prior-year period.
The company also faces additional interest obligations tied to a new £450 million term loan, part of a broader £550 million debt financing package priced at 6.75% above the SONIA base rate and maturing in July 2031.
Net debt reached £1.57 billion as of September 30, up from £1.38 billion at the close of December, driven primarily by the increase in gross borrowings.
Despite those pressures, revenue climbed 36% to £388.7 million in the quarter, powered largely by the arrival of the Valhalla hypercar, which contributed 127 deliveries and helped lift overall wholesale volumes to 1,431 units.
Gross margin expanded sharply to 37.4% from 29% a year earlier, nearly matching the analyst estimate of 37.5% and reflecting the high value attached to each Valhalla unit.
Core-model volumes told a more complicated story, falling 9% to 1,304 vehicles from 1,428, a production-pace adjustment the company had signalled since the second quarter.
SUV demand weakened further, with volumes dropping 14%, while sales across Europe, the Middle East and Africa excluding Britain contracted by 20% during the period.
The adjusted EBIT loss narrowed to £24.9 million from £50.6 million a year earlier, coming in slightly better than the £27 million loss analysts had pencilled in, suggesting operational execution is improving even as financing costs drag.
Free cash outflow shrank to £27.6 million from £94 million in the comparable quarter, a result that nearly matched the £28 million estimate and points to tighter cash management across the business.
Against that backdrop, management held firm on its full-year 2026 targets, which include total wholesale volumes broadly in line with 2025’s 5,448 units and approximately 500 Valhalla Coupe deliveries over the year.
The company is targeting a gross margin in the high 30s percentage range, a significant step up from 29% in 2025, alongside an adjusted EBIT margin that is expected to move “towards breakeven” from negative 15% last year.
Capital expenditure guidance was trimmed to around £300 million from £341 million spent in 2025, and the five-year investment plan through 2030 was revised down to approximately £1.7 billion from a prior figure of around £2 billion.
Chief executive Adrian Hallmark struck an optimistic tone, pointing to what he described as “tangible and consistent progress,” adding that “we expect this momentum to continue into Q4 and beyond.”