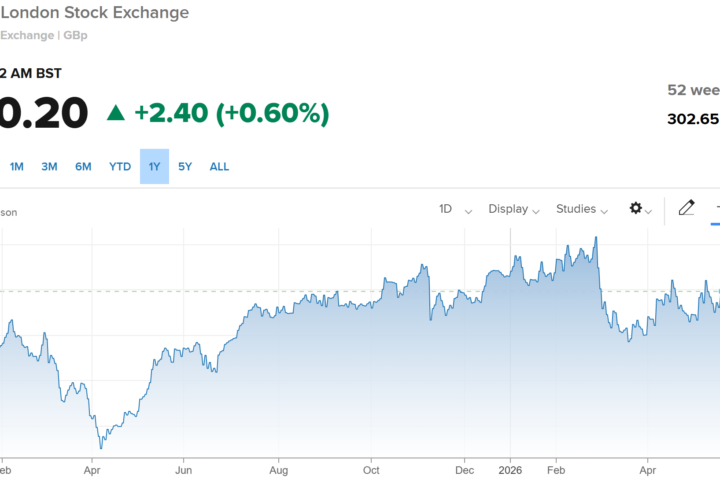
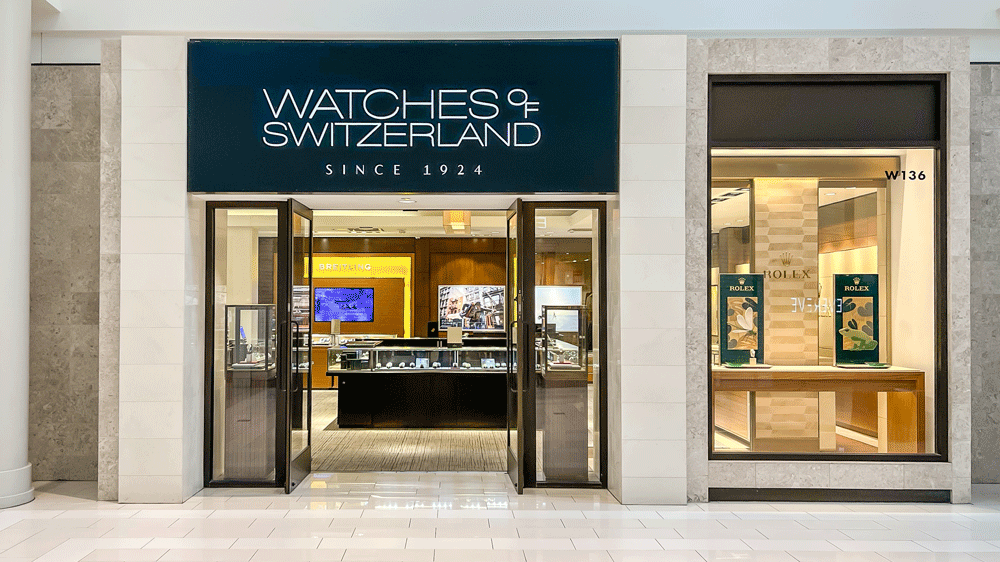
Watches of Switzerland Group (LSE:WOSG) slashed its net debt by £88 million over twelve months, bringing the balance down to just £24 million as of November 1, 2026.
That balance sheet improvement accompanied a surge in profitability, with adjusted EBIT projected at between £87 million and £89 million, roughly 28% above the prior-year figure.
The margin picture also brightened, with adjusted EBIT margin expected to widen by 80 to 100 basis points compared with the same period a year ago.
Chief Executive Brian Duffy described a period that exceeded internal targets, noting that revenue gains fed directly through to stronger cash generation and higher profitability across both markets.
Total group revenue for the 26 weeks ended November 1, 2026, reached £974 million, up 15% from £845 million on both a reported and constant-currency basis.
The American business was the primary growth engine, generating £501 million in revenue, a 22% advance at constant currency, with retail sales alone climbing 24% to £442 million.
The Deutsch and Deutsch acquisition bolstered those US figures, though Roberto Coin wholesale activity also contributed, with that segment posting revenues of £65 million, up 15%, alongside the opening of its first two partner shop-in-shops during October.
New showroom projects in Marlton, New Jersey, and Avalon, Georgia, added further physical footprint to the group’s expanding American network.
Back in the UK, revenue reached £473 million, growing 9% from £436 million, supported by certified pre-owned watches and a particularly strong showing in luxury jewellery through the group’s showrooms.
Jewellery across the group rose 20% on a reported basis to £123 million, while showroom-specific jewellery sales jumped 31% at constant currency, making it one of the fastest-growing product lines in the period.
Luxury watch revenue, the group’s largest category at £812 million, advanced 15%, while services and ancillary activities contributed £39 million, a 9% increase year-on-year.
UK store investment continued throughout the half, with a Rolex boutique in Glasgow receiving an expansion and Goldsmiths locations in Watford, Chelmsford, and Exeter undergoing refurbishment.
On the back of these results, management lifted the lower bound of its full-year revenue growth forecast, with FY2027 guidance now set at 7% to 10% constant-currency growth, compared with a prior range of 5% to 10%.
The expected adjusted EBIT margin expansion for the full year was similarly tightened upward, moving to a range of 60 to 80 basis points from the previous 40 to 80 basis points.
Capital expenditure guidance held firm at £60 million to £70 million, and free cash flow conversion is anticipated at approximately 70% for the full year.
Management cautioned that second-half revenue growth will likely trail the first half, partly because the comparison period includes one additional trading week and partly due to the Deutsch and Deutsch acquisition lapping its anniversary in January.
Despite maintaining a measured outlook given broader macroeconomic pressures, the group said trading momentum remained constructive across both its UK and US operations.
Investors and analysts will get the complete picture when Watches of Switzerland publishes its full interim results on December 10, 2026.